From Bitcoin Reserve to Treasury Governance: What the US Bill Signals for Institutions
The United States has taken another step towards formalising Bitcoin within the public sector’s financial architecture.
On 17 September 2026, the US House Committee on Financial Services approved the American Reserve Modernization Act of 2026 by 28 votes to 21. The bill would establish a Strategic Bitcoin Reserve and a separate Digital Asset Stockpile within the US Department of the Treasury. It would also require federal agencies to account for digital assets under their control, publish quarterly proof-of-reserve reports and undergo third-party audits.
The bill still needs to pass the full House and Senate before it can become law. Its committee approval therefore represents an important policy signal rather than a completed legislative outcome.
For institutions, however, the significance extends beyond the immediate question of whether the US government will hold Bitcoin.
The deeper question is becoming increasingly practical:
How should organisations govern digital assets as part of a broader treasury strategy?
From seized assets to strategic reserves
The proposed legislation would place Bitcoin acquired through civil and criminal forfeiture into a reserve structure, with assets held for a minimum of 20 years. It would also create a separate stockpile for other digital assets obtained through forfeiture.
This distinction matters.
A government may initially hold digital assets because they were seized or transferred through legal proceedings. That does not automatically make those assets part of a deliberate investment or reserve strategy.
A treasury reserve involves a different set of questions:
What is the purpose of holding the asset?
Which assets qualify?
Who has authority to approve acquisitions, transfers or disposals?
How are custody arrangements selected and reviewed?
What liquidity must remain available?
How are price volatility and concentration risk managed?
What reporting is required?
How does the organisation respond to forks, staking, network upgrades or operational incidents?
The American Reserve Modernization Act places several of these issues directly into the policy conversation. Its proposed accounting, proof-of-reserve and audit requirements recognise that ownership is only one part of responsible digital asset management.
Governance is the other.
The institutional treasury question
For companies, industry associations, foundations and other institutions, digital asset treasury is no longer limited to a question of whether to buy Bitcoin.
It is becoming an organisational design question.
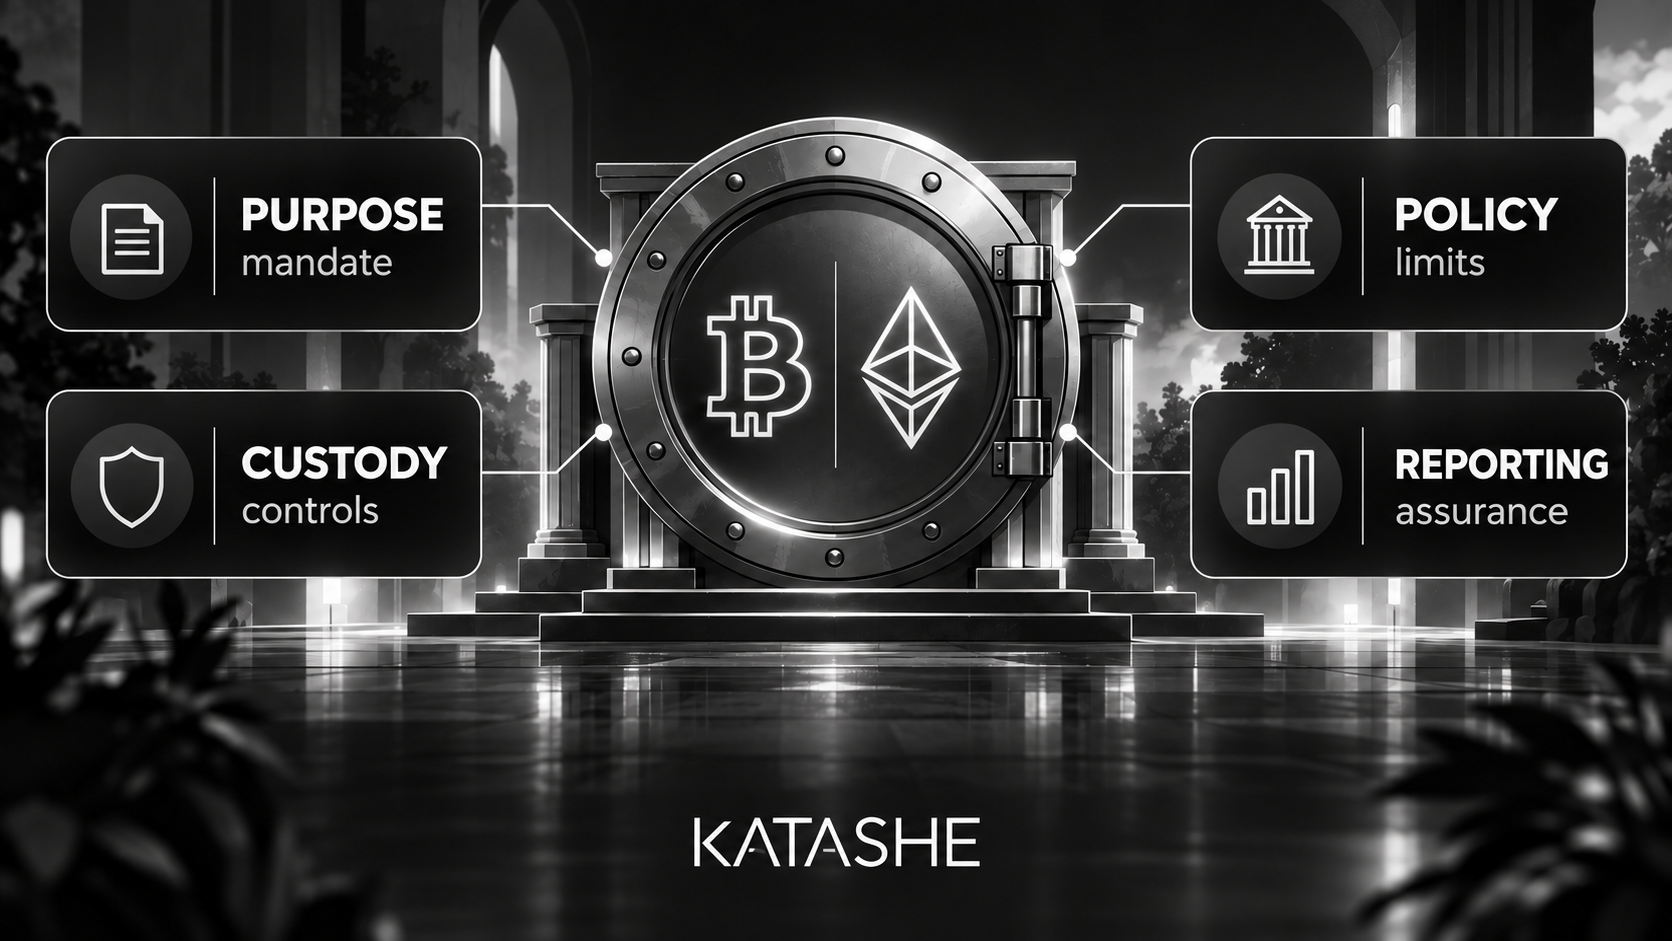
A credible treasury programme requires alignment across:
Purpose
The institution should define why it is holding digital assets. The objective may include long-term reserves, diversification, ecosystem alignment, operational use, liquidity management or participation in a digital economy.Asset policy
The institution should establish which assets may be held and why. Bitcoin, Ether, stablecoins and tokenised instruments each carry different liquidity, custody, governance and technology considerations.Decision rights
Boards, management teams, treasury committees and operational teams should have clearly defined responsibilities. Approval authority, escalation procedures and delegated execution limits should be documented before transactions take place.Custody and control
The custody model should reflect the institution’s risk profile. Options may include regulated third-party custody, institutional wallets, multisignature arrangements, self-custody or a combination of these approaches. Key management, access controls, segregation of duties and recovery procedures require particular attention.Risk management
Treasury policies should address market volatility, counterparty exposure, liquidity needs, technology risk, sanctions and financial crime controls, tax treatment, accounting and regulatory reporting.Transparency
Regular reporting should allow stakeholders to understand what the institution holds, where assets are held, how they are valued and what controls apply. The proposed US quarterly proof-of-reserve and audit requirements illustrate the direction of travel.
Why public-sector action matters to private institutions
Public-sector reserve policy can influence private-sector behaviour in several ways.
First, it can help establish digital assets as a subject of mainstream treasury policy rather than a niche investment discussion.
Second, it creates pressure for stronger operating standards. Once a government is expected to account for digital assets, demonstrate control and report reserves, similar expectations may emerge across financial institutions, corporates, associations and foundations.
Third, it highlights the importance of institutional infrastructure. Digital asset adoption requires more than market access. It requires custody, valuation, governance, assurance, reporting and clearly documented accountability.
Finally, public-sector decisions may influence how boards and investment committees assess the strategic relevance of digital assets. Institutions may increasingly ask whether they have an appropriate policy, even when they decide not to hold digital assets.
A decision to hold no digital assets should also be a considered governance decision, supported by a clear rationale and periodic review.
Bitcoin reserves and broader digital asset treasuries
The US proposal is centred on Bitcoin. Institutional treasury policy may need to consider a broader range of digital assets, each serving different functions.
This does not mean every institution should hold every category.
The relevant question is whether the asset serves a defined institutional purpose and whether the organisation can govern the associated risks.
A treasury framework should therefore distinguish between:
assets held as reserves;
assets held for liquidity;
assets used in operations;
assets received through business activity or legal proceedings; and
assets held temporarily pending disposal or transfer.
Each category may require different controls, reporting and decision rights.
The role of the board
Digital asset treasury should sit within the institution’s existing governance architecture.
The board does not need to manage every transaction. It does, however, need sufficient visibility to understand:
the purpose and scope of the programme;
the institution’s risk appetite;
the delegated authority structure;
the custody and control environment;
the reporting and assurance model;
the circumstances requiring board escalation.
This is particularly important because digital assets can combine financial, technological, legal and operational risks in a single activity.
For example, a treasury decision may involve:
an investment assessment;
a custody arrangement;
a wallet approval process;
a smart contract interaction;
a regulatory classification;
a tax or accounting treatment; and
a communications decision.
These responsibilities should connect through a coherent control framework rather than sit in isolated workstreams.
What institutions can do now
Institutions considering a digital asset treasury programme can begin with a structured readiness review.
1. Define the mandate
Document the purpose of the treasury programme, the institution’s time horizon and the circumstances in which digital assets may be acquired, held, transferred or disposed of.
2. Establish a policy framework
Create a policy covering permitted assets, limits, liquidity requirements, counterparty exposure, custody, valuation, reporting and escalation.
3. Map accountability
Clarify the roles of the board, management, treasury or finance function, risk and compliance teams, technology teams and external providers.
4. Assess custody options
Evaluate custody models against the institution’s size, capabilities, operational resilience requirements and regulatory expectations.
5. Build reporting before transacting
Define the information the board and stakeholders will receive. Reporting should cover balances, valuation, custody locations, transactions, permissions, incidents and policy exceptions.
6. Test the operating model
Conduct tabletop exercises for scenarios such as a compromised key, unavailable custodian, sharp market movement, network disruption, mistaken transfer or urgent liquidity requirement.
7. Review regularly
Digital asset policies should evolve as regulation, market infrastructure, institutional objectives and technology change.
A strategic reserve is a governance commitment
The US bill’s most important implication may be its emphasis on institutional control.
A digital asset reserve cannot be defined solely by the asset held. It is defined by the policy, authority, infrastructure and accountability surrounding that asset.
This is relevant to governments, but it is equally relevant to companies, industry bodies, foundations and other organisations exploring how digital assets may fit within their financial and operational strategies.
At Katashe Solutions, we see digital asset treasury as part of a broader governance question: how institutions can engage with digital assets in a way that is purposeful, accountable and operationally credible.
The next stage of adoption will require institutions to move beyond the question of whether digital assets belong in the treasury conversation.
They will need to determine what responsible ownership looks like in practice.
This article is for general information only and does not constitute investment, legal, tax or financial advice. The American Reserve Modernization Act of 2026 remained subject to further legislative approval at the time of publication.